
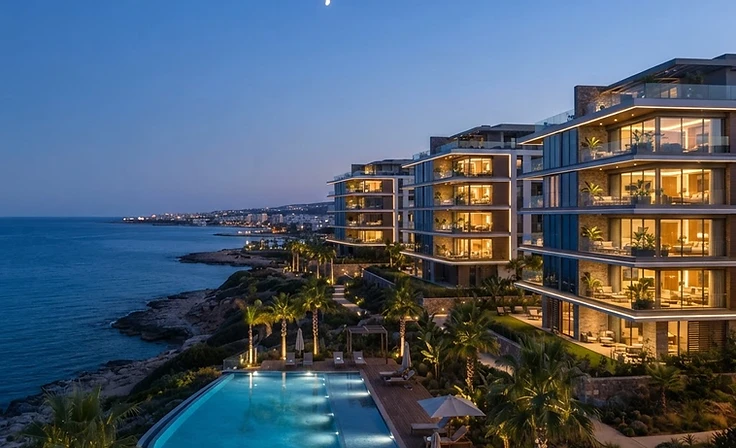
Cyprus real estate is booming, but financing remains the biggest hurdle. Here are the three main financing options for Israeli investors.
The Cyprus real estate market is booming, and many Israelis recognize the yield and appreciation potential. Yet financing remains the greatest challenge. Since European banks tighten their terms for non-residents, at Betterate we built a strategy presenting the three main financing alternatives available to the Israeli investor.
1. A mortgage from a local Cypriot bank (Cyprus Mortgage)
Despite the challenges, obtaining a mortgage from a Cypriot bank is entirely possible — especially at banks like Hellenic Bank and Bank of Cyprus — provided the file is presented correctly.
- Required equity: typically 30% to 50%, depending on whether the property is a new build or a second-hand home.
- Income proof: the local bank reviews employment stability, tax assessments (for the self-employed), and at least six months of current-account statements. Notarized translation of documents is required.
- Advantage: a euro-denominated loan reduces exposure to exchange-rate fluctuations if rental income is also in euros.
2. Leveraging an existing property in Israel (any-purpose loan)
This is sometimes the fastest and most flexible route. If you own an apartment in Israel with a low mortgage or none at all, you can mortgage it to fund the Cyprus purchase.
- How it works: the Israeli bank grants an "any-purpose loan" of up to 50% of your existing property's value (less any existing mortgage).
- Main advantage: the funds arrive directly in your Israeli account, and you reach Cyprus as a "cash buyer" — giving you significant bargaining power with the seller.
3. Installment plan with the developer (Off-Plan)
When buying a property "off-plan", many developers in Cyprus allow a convenient installment plan that eliminates the need for a bank mortgage in the early stages.
- Payment structure: typically 30%-40% on signing, and the rest in installments tied to construction progress.
- Combined strategy: pay the equity during construction stages, and take a mortgage on the balance just before receiving the keys.
Which financing route suits you?
Every investor has a unique financial profile. Don't compromise on high rates or accept a bank rejection. Leave your details and we'll build a cross-border financing strategy for you.
Click here for a free consultationContact for Consultation
Have questions about financing your property? Speak with an advisor.
Request assessment